
Simulator golf has moved into the mainstream of golf participation, according to new research from software provider Golf Genius. Venues are expanding quickly across international markets, and operators are increasingly turning to memberships, leagues and software to encourage repeat play and recurring revenue.
The Simulator Golf Market Insights Report was produced with global golf solutions platform ION 54 and sports participation platform experts played.co. It mapped 2,683 venues and 9,580 simulator bays across 12 countries and 238 cities in Japan, Scandinavia, the UK and Ireland, and Australia and New Zealand. The United States and South Korea are not covered in this edition.
The report shows a market growing in both size and maturity. Some 43 percent of venues have opened since 2020, and global growth in simulator golf is projected at eight to 10 percent a year to 2030.

Simulator venues have traditionally been promoted as social spaces built around informal play and food and drink. The report argues that structured competition, integrated software and cross-venue activity will drive the sector’s next phase of growth, and will become an important participation tool for venues and national federations alike.
Hardware is already well established, but software has yet to catch up. Some 71 percent of mapped venues have known hardware technology and 73 percent have booking infrastructure, but only 11 percent have a recorded competition or league platform and just 0.5 percent have a CRM system or app.
Demand is concentrated in the evenings and at weekends, with average off-peak use of around 20 percent. The report finds that the most mature venues use memberships, leagues, coaching, events and connected player technology to turn single sessions into repeat participation and more predictable income. “The most commercially advanced simulator golf venues are now selling a sense of belonging, not hours,” it says.
Six key stats
- There are an estimated 102 million off-course golfers worldwide and around 15,000 simulator venues globally.
- 43 percent of venue openings came after 2020, partly accelerated by the pandemic.
- Scandinavia is the most advanced region studied, based on service diversity, technology adoption, venue density and multi-site market penetration.
- Japan is the largest studied market, with 1,033 venues. Tokyo alone has 365, more than Australia and New Zealand combined.
- The median price of a simulator bay is about £21 per hour.
- 58 percent of venues offer memberships, but only 32 percent run any form of league.
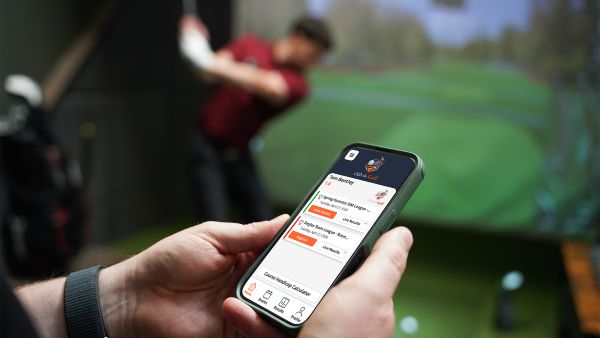
For national federations, the report says player identity, simulator handicaps and cross-venue initiatives run at national level can turn first-time visits into sustained participation.
Frank Kirsten, Chief Executive of PGA Holland, said: “The opportunity for simulator golf is not simply about getting players through the door once, but creating reasons for them to keep coming back. This report provides valuable insight into how different markets are approaching that challenge, highlighting the role that structured play, technology and connected experiences can play in driving repeat participation.
“We are seeing this first-hand in the Netherlands, where PGA Holland is now running a national programme of cross-venue simulator leagues to drive repeat play and the adoption of simulator handicaps. The findings of this research reinforce the importance of creating more connected and engaging experiences for players, while demonstrating how these opportunities can be translated into practical initiatives at a national level.”
Sean Dainty, Managing Director, International, at Golf Genius, said: “This research gives the golf industry its clearest picture yet of how quickly simulator golf has developed internationally. What stands out is the scale of the opportunity for operators and golf federations alike.
“The venues that can give players reasons to return, be it through leagues, memberships, coaching and other digital experiences will be the ones best placed to turn growing participation into sustainable, recurring revenue.”
The report concludes that simulator golf is no longer an emerging format but a key gateway to new participation, player retention and commercial opportunity. With hardware established, it says the next phase will depend on software that links players, formats and revenue streams within and across venues.


Leave a Reply